Why "Call Everyone" Breaks, and What Replaces It
Ask a Medicare agency how they handle AEP retention and you will usually get some version of the same answer: starting October 1, every agent gets a list and works through it until AEP ends.
It is an honest answer and a reasonable instinct. When plan exits are running at ten times historical levels, wanting to touch every member makes sense.
It also does not survive contact with a calendar.
The arithmetic
Take a 15,000 member book. AEP runs 54 days. Say 20 agents making 40 dials a day.
That is 800 dials a day and about 43,000 across the window, which looks like enough to reach every member almost three times. On a spreadsheet the plan works.
Now add reality. A retention call with an engaged member runs 15 to 20 minutes, not 4. Those same agents are writing new business during the highest-volume selling window of the year. Contact rates on first attempt are nowhere near 100%, so a real conversation costs three or four dials. And the agents are working the list in whatever order it came out of the AMS.
Meanwhile, on a book that looks like the 2026 national picture, roughly 10% of those 15,000 members are on plans that exited, a further share sit in counties a surviving plan dropped, and another 5% to 10% are on plans that stayed but cut something the member will notice. Call it 3,000 to 4,000 members who genuinely need an intervention.
Work the list sequentially and a member whose plan terminated in a rural county with 3 alternatives gets reached in week 4, after an agent spent two full days reassuring members whose coverage did not change at all.
Tiering, and what actually goes in each tier
Tier 1 is anyone losing coverage outright. Plan terminated, or the member's county was dropped from the service area. There is no version of doing nothing that ends well for these members. They need a personal call in the first week of the window, with a replacement already identified and the benefit differences understood before the phone rings. On a book sitting in disrupted counties this tier can run well into double digits as a share of members, and it carries most of the retention risk in the book.
Tier 2 is anyone whose plan survived but got worse in a way the member will notice. MOOP up meaningfully, Part B giveback eliminated, dental or vision or OTC cut back. These members still have coverage, so nothing forces the conversation. They are also the members most likely to respond to a competitor's ad in November. If they are going to shop, it is better that they shop with you.
Tier 3 is a stable, well-rated plan with no material change. A touchpoint is appropriate. A 20-minute consultation is not.
Where this gets hardest: rural books
Urban retention is a filtering exercise. The member has 40 options, most of them reasonable, and the agent narrows to the best fit.
Rural retention is a matching exercise with almost no slack. The member might have 3 options, and the gaps between them are material. One drops the regional hospital system the member has used for 20 years. One raises the specialist copay by $20 on a member who sees a cardiologist monthly. One quietly ends a $75 monthly Part B giveback the member has been treating as income.
Telling that member their new plan is similar is not a conversation. It is the moment they start shopping. What works is specificity: here are the 3 plans in your county, here is the one closest to what you have, here is exactly what improves and exactly what gets worse.
Worth saying, because it cuts the other way too: rural members are frequently the most durable book an agency has. Longer relationships, higher trust, far less shopping behavior than in dense urban markets where a member sees a Medicare ad every commercial break from October through December. The retention outcome in rural markets is unusually sensitive to timing. Reach a rural member in early September with a clear recommendation and you are the trusted advisor handling it. Reach them in late October, after three weeks of worry and two competitor mailers, and you are one voice among several.
The advantage is not that rural members are harder to keep. It is that they are easier to keep, if you get there first. And since rural members were disrupted at roughly twice the rate in the 2026 cycle, a rural-weighted book has more of them in play.
The last mile: what the agent sees
There is a moment in every retention call that decides the outcome. It is not the introduction and it is not the explanation. It is when the member says "so what should I do?"
In most agencies, what the agent has on screen at that moment is the member's name, their current plan name, and a list of plans available in their ZIP code. That produces the worst possible answer: "let me look into that and call you back."
What the agent should be able to say is specific. Something closer to: I looked at the 4 plans available in your county, and the closest match to what you have now is Plan X. Your MOOP stays at $3,400, you keep dental and vision, your specialist copay goes from $35 to $45, and you pick up a $75 monthly Part B giveback your current plan does not offer.
That is a retention conversation. The first version is a callback the member may not take, during the exact weeks a competitor is spending heavily to reach them.
Why most agencies cannot do this
Not for lack of will. Producing that screen means joining 9 separate CMS and HUD datasets, then scoring every available plan in the county against the one the member is losing on premium, star quality, benefit overlap and carrier continuity. The files arrive tab-delimited, keyed inconsistently between sources, with column names written for a CMS analyst rather than an agent.
No agent does that by hand. No spreadsheet does it at scale.
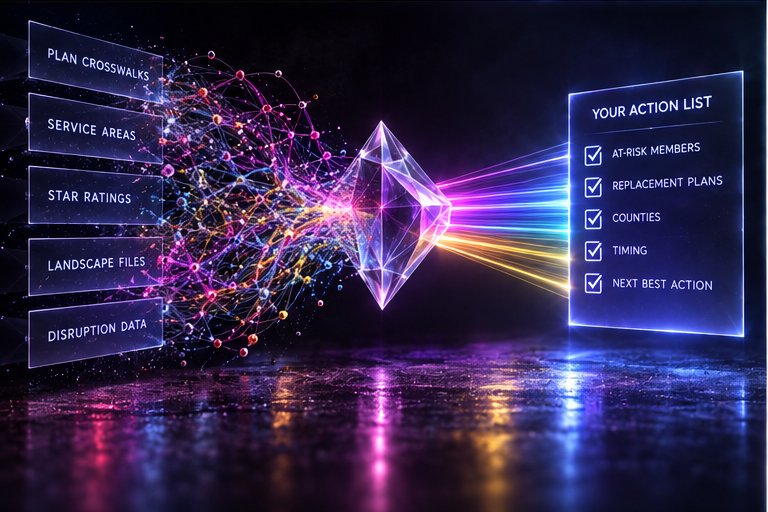
ShieldLync joins the crosswalk, service area, landscape, star rating, enrollment, contract and ZIP-to-county files, pre-computes the top 5 replacements for every at-risk plan and county, then generates the tiered list and the member-level comparison view. The agent opens one screen with the disruption reason, the ranked replacement options and the talking points for the call.
The point
"Call everyone" is a strategy built from good intentions and missing data. In a market moving 2.9 million members, the constraint is not effort. It is knowing which 3,000 of your 15,000 members need the first two weeks of the window.
That question has an answer, and it is sitting in public CMS files right now.
Ready to score your leads?
See how RiskLync can reduce your CPA with predictive lead scoring.